


The 2026 Public Charge Rule: What Green Card Applicants Should Know Before September 18
Starting September 18, 2026, USCIS will evaluate adjustment-of-status applicants under a substantially broader public charge standard. One that can consider non-cash benefits like Medicaid, SNAP, and housing assistance, and that replaces the narrow 2022 framework with wide officer discretion. For most employment-based and investor applicants, the practical answer is preparation, not alarm: the test remains a totality-of-circumstances judgment in which no single factor is disqualifying, and a well-documented financial record answers it. But the change is real, the effective date is firm, and the filing-timing decision it creates should be made deliberately.
By Origin Law P.C. | August 24, 2026
What actually changed
The July 2026 final rule rescinds the 2022 regulations, which had defined “likely to become a public charge” narrowly: primary dependence on government cash assistance or long-term institutionalization, with entire categories of benefits expressly off the table. The 2026 rule removes that bright line. Under USCIS’s implementing guidance (issued August 18), the framework is transitional: for cases governed by the pre-September 18 standard, only cash assistance for income maintenance and long-term institutionalization count; on or after September 18, officers may consider the full range of means-tested benefits, including categories the prior rule excluded, such as Medicaid, CHIP, SNAP, and housing assistance.
The statutory factors themselves are unchanged, because they come from the Immigration and Nationality Act: age; health; family status; assets, resources, and financial status; and education and skills. What changed is the evidentiary aperture around them and the discretion officers hold in weighing the whole.
Who should pay attention, and who shouldn’t panic
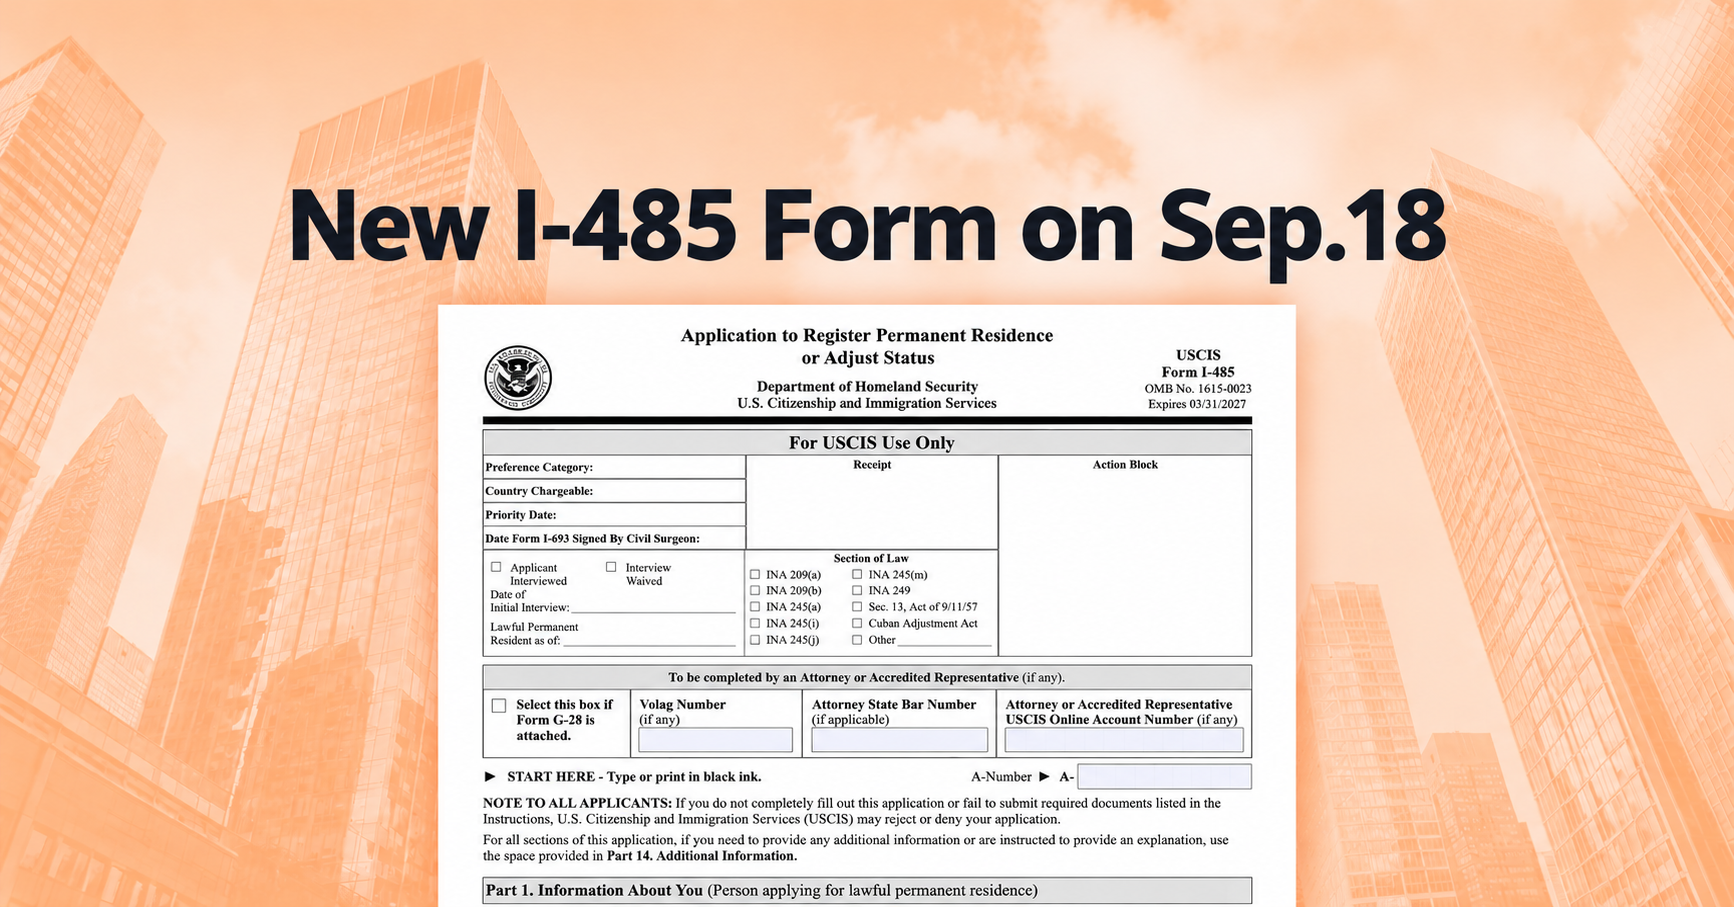
The public charge ground applies to admission and adjustment, not to every benefit interaction, and statutory exemptions (refugees, asylees, and certain other categories) are untouched. For the clients we serve. Employment-based professionals, investors, founders. The realistic exposure is usually not benefits history at all but documentation: the new Form I-485 asks expanded questions about household finances, insurance, and benefits, and an incomplete or internally inconsistent answer set is the avoidable risk. An EB-5 investor who has just documented an $800,000 lawful source of funds, or an H-1B professional with years of W-2s, has a strong public charge record by construction, if the filing presents it.
The harder conversations are for mixed households and for families where a U.S.-citizen child has received benefits. Two principles matter there. First, benefits received by other household members are not the applicant’s receipt, but household finances are a statutory factor, so the presentation needs care rather than avoidance. Second, the well-documented “chilling effect”. Eligible families dropping benefits out of fear. Is usually the wrong response; whether any particular benefit interaction matters to any particular application is a case-specific question worth an hour of counsel before a family forgoes healthcare or food assistance it lawfully qualifies for.
The bond mechanism returns
The rule revives a practical role for public charge bonds: where an officer finds the factors adverse, USCIS may offer a bond (Form I-945) as a path to approval rather than denial, with amounts set case by case. Bond terms deserve scrutiny. Breach findings can now rest on means-tested benefit receipt, and cancellation requires an affirmative filing after five years. A bond is a tool, not a trap, but it is a tool with a long tail.
What we’re advising clients to do
Applicants ready to file before September 18 should complete their filings under the current framework and the current form edition. See our companion piece on the I-485 edition cutover, which has no grace period. Applicants filing after should treat the financial exhibit set as a first-class part of the petition: evidence of assets and income, health coverage, household composition, and, where there is any benefits history in the household. A short, factual explanation rather than silence. Discretion is answered with documentation. The applicants who struggle under discretionary regimes are rarely the ones with imperfect facts; they are the ones with unexplained facts.
Frequently asked questions
Do benefits my U.S.-citizen children received count against me? Receipt by household members is not attributed to the applicant as receipt, but household financial circumstances are a statutory factor. The right approach is accurate disclosure with context, not omission.
Does using Medicaid or SNAP before September 18 hurt an application filed after? The guidance directs officers to the expanded framework for post-September 18 adjudications, and benefit history is evaluated within the totality of circumstances. Timing, duration, and current self-sufficiency all bear on the weight. This is precisely the kind of fact pattern to review with counsel before filing.
I’m an EB-5 investor / H-1B professional. How worried should I be? For well-documented employment-based and investor applicants, this is mostly a documentation standard, not a barrier. The investment capital, income history, and insurance record that already exist in your file are the answer. Presented deliberately.
Is the rule being challenged? Litigation over this administration’s immigration rulemaking is active on several fronts, and challenges to public charge policy have a long history. Plan around the rule as written and effective September 18; treat any future injunction as upside, not strategy.
Attorney advertising; general information, not legal advice.